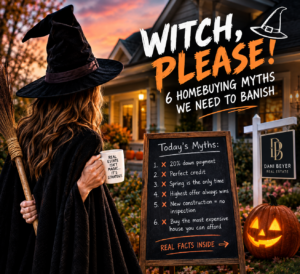
 Think you need 20% down, a perfect credit score, and a full moon to buy a house? Let’s separate real estate facts from spooky fiction.
Buying a house can feel a little like entering a haunted mansion. There are unfamiliar terms, mysterious paperwork, numbers that make your eyes water, and at least one person telling you what you absolutely must do.
“You can’t buy without 20% down!”
“Never buy a house in the fall!”
“New construction means you don’t need an inspection!”
Witch, please.
At Dani Beyer Real Estate, we’d love to help you banish some of the most persistent homebuying myths out there. Because whether you’re a first-time buyer, moving up to a bigger house, or relocating to Kansas City, you deserve advice based on facts—not real estate folklore passed down from your cousin’s neighbor’s former coworker.
Grab your broom. We’re sweeping these six myths right out the front door.
Myth #1: You Need a 20% Down Payment to Buy a House
The myth: If you don’t have 20% of the purchase price sitting in your bank account, you aren’t ready to buy.
The reality: A 20% down payment can be beneficial, but it isn’t a universal requirement.
Some conventional mortgage programs allow eligible buyers to put down as little as 3%. FHA loans generally allow eligible borrowers to put down as little as 3.5%, and VA and USDA loans may offer zero-down options to qualifying borrowers.
Of course, the amount you can put down depends on the loan program, your financial situation, and the property’s eligibility. A smaller down payment may also mean a higher monthly payment and, depending on the loan, mortgage insurance.
And don’t forget closing costs, moving expenses, and the money you’ll want to keep in reserve for the occasional homeownership surprise.
The takeaway: Don’t assume you’re years away from buying simply because you haven’t saved 20%. Talk with a qualified lender to understand which options may fit your circumstances.
Banish this myth by: Exploring your financing options before ruling yourself out. You might be closer to homeownership than you think.
Myth #2: You Need Perfect Credit to Get a Mortgage
The myth: Unless your credit score is practically glowing, lenders will slam the door in your face.
The reality: You generally don’t need perfect credit to qualify for a mortgage. Different loan programs have different credit requirements, and lenders may consider other aspects of your financial picture, including income, debt, assets, and payment history.
A stronger credit profile can help you qualify for more favorable terms, but the score you need depends on the loan program and lender. There isn’t one magic number that guarantees approval for everyone.
If your credit needs some attention, that doesn’t automatically mean homeownership is off the table. It may simply mean you need a plan and a little time.
The takeaway: A lender can help you understand where you stand, what loan programs might be available, and which steps could improve your application.
Banish this myth by: Getting an honest assessment of your financial situation instead of letting an internet stranger’s credit score dictate your future.
 Myth #3: Spring Is the Only Time to Buy a House
The myth: If you aren’t house hunting in the spring, you’ve missed your chance. Close the laptop. Put away the Zillow app. Try again next year.
The reality: Spring often brings more homes to the market and more buyer activity, but it isn’t automatically the best season for every buyer.
In the Kansas City area, the number of available homes, competition, pricing, and negotiating opportunities can vary by neighborhood, price range, and year. Fall and winter may bring fewer listings in some areas, but they can also bring buyers who are more serious about moving.
The right time to buy depends on your finances, your housing needs, your timeline, and the conditions in the specific market you’re shopping.
Need to move because of a new job, a growing family, or a lease ending? Waiting for the perfect season may not be the most practical choice.
On the other hand, if you have flexibility, using that time to save, improve your credit, or research neighborhoods can be worthwhile.
The takeaway: There is no universally perfect month to buy a house. There is a time that makes sense for your life and financial situation.
Banish this myth by: Focusing on your readiness and the current market conditions—not a calendar superstition.
Myth #4: The Highest Offer Always Wins
The myth: If you want a house badly enough, just throw more money at the seller. Problem solved.
The reality: Price matters, but it isn’t the only factor a seller considers.
Depending on the transaction, sellers may also consider financing strength, appraisal and inspection terms, contingencies, the proposed closing date, possession arrangements, and the likelihood that the deal will actually make it to closing.
For example, imagine two offers on a Kansas City home. One offers a slightly higher price but includes several conditions that introduce uncertainty. Another offers a competitive price with financing already well underway and a closing timeline that fits the seller’s plans.
The seller may prefer either offer, depending on the circumstances. There is no guarantee that the highest number will win.
That doesn’t mean you should waive every protection or promise terms you can’t comfortably meet. An aggressive offer can become a very expensive plot twist if the financing, appraisal, or property condition doesn’t cooperate.
The takeaway: A strong offer is about more than the price. It should balance competitiveness with your financial comfort and the protections that matter to you.
Banish this myth by: Working with your agent to understand the seller’s priorities and structure an offer that makes sense for both the opportunity and your budget.
 Myth #5: New Construction Means No Problems—and No Inspection Needed
The myth: It’s a brand-new house. Nobody has lived there. Everything must be perfect, right?
The reality: New construction can offer modern layouts, new systems, energy-efficient features, and the opportunity to personalize certain finishes. But new doesn’t automatically mean flawless.
Construction involves many trades, materials, inspections, and moving parts. Workmanship issues, installation problems, incomplete items, and defects can still occur.
Municipal building inspections and a builder’s warranty serve different purposes from an independent home inspection. A qualified inspector can provide another perspective on the home’s condition at the time of the inspection.
If you’re buying new construction around Kansas City, it’s also worth understanding the builder’s contract, included features, upgrade costs, completion timeline, warranty terms, and any restrictions on outside inspections.
And remember: That gorgeous model home may include upgrades that aren’t part of the base price. The staged furniture probably isn’t included either. Sorry.
The takeaway: New construction can be a great option, but you should still understand what you’re buying and what recourse you have if something isn’t right.
Banish this myth by: Asking about independent inspections, warranty coverage, construction timelines, and the exact features included in your contract.
Myth #6: You Should Always Buy the Most Expensive House You Can Afford
The myth: If the bank approves you for a certain amount, that’s how much you should spend. Why leave money on the table?
The reality: A mortgage preapproval helps establish a potential borrowing limit. It doesn’t tell you what monthly payment will feel comfortable once the rest of your life gets involved.
Lenders evaluate your finances using their qualification criteria. Your personal budget also needs to account for groceries, transportation, childcare, travel, savings goals, retirement contributions, and whatever expensive hobby your household has recently adopted.
Then there’s the house itself.
A higher-priced home may come with higher property taxes, insurance premiums, utility bills, maintenance costs, or HOA dues. Two homes with similar purchase prices can have very different ongoing expenses.
And if you’re relocating to Kansas City, don’t forget to compare the full cost of living and your likely commute, not just the mortgage payment.
You want to enjoy your home. You probably don’t want to spend every Saturday admiring the kitchen while eating instant noodles because the house consumed your entire budget.
The takeaway: Your maximum approved loan amount and your ideal home budget are two different things.
Banish this myth by: Establishing a comfortable monthly budget before you shop, including estimated taxes, insurance, utilities, HOA fees, and maintenance. Leave yourself room to live your life outside the house, too.
 Bonus Myth: You Need to Have Everything Figured Out Before Talking to a Realtor
The myth: You need a firm timeline, a fully formed wish list, a lender, and a spreadsheet with every neighborhood ranked before you’re allowed to ask for help.
The reality: You can start with questions.
Maybe you’re curious about whether buying makes sense compared with renting. Maybe you’re considering a move to the Kansas City Northland but don’t know which communities fit your budget. Maybe you’re a year or two away and want to understand what to do now to prepare.
Those are all perfectly reasonable places to start.
A good real estate conversation shouldn’t require you to make a commitment you’re not ready for. It should help you understand your options, identify your next steps, and decide whether buying makes sense for you.
Banish this myth by: Asking questions early. Getting information doesn’t mean you’re obligated to buy a house tomorrow.
Ready to Banish the Homebuying Myths?
Buying a home is a big decision. It can be exciting, overwhelming, and occasionally terrifying—especially when everyone seems to have a different opinion about how you’re supposed to do it.
At Dani Beyer Real Estate, we’re here to help Kansas City buyers separate fact from fiction, understand their options, and navigate the process with a little more confidence and a lot less unnecessary drama.
Whether you’re ready to start touring homes or simply wondering what buying might look like someday, we’re happy to help you figure out your next step.
No crystal ball required. Just good information, a solid plan, and a real estate team in your corner.
Ready to start your Kansas City homebuying journey? Connect with Dani Beyer Real Estate and let’s talk about what’s possible.
Happy myth-busting! 🧹
Dani Beyer is a Kansas City native, experienced REALTOR®, and CEO and Lead Listing Specialist of Dani Beyer Real Estate, brokered by Keller Williams KC North. With over 20 years of real estate experience, Dani has helped thousands of buyers and sellers navigate the Kansas City housing market. Specializing in Kansas City Northland real estate, including Parkville, Platte County, and Clay County, Dani is known for her local market expertise, strategic home-selling approach, and commitment to exceptional client service. Backed by more than 1,050 five-star Google reviews, Dani and her team are trusted resources for buying, selling, and relocating throughout the Kansas City metro area.